For many high-net-worth borrowers, the challenge isn’t a lack of wealth. It’s turning complex, international and often illiquid assets into usable capital without dismantling a long-term investment strategy.
That is the territory occupied by Enness Global, the specialist finance broker founded by CEO Islay Robinson in 2007. From large mortgages and bridging loans to crypto-backed lending and finance secured against fine art, yachts and supercars, the firm sits in a part of the market where standard banking products often don’t reach.
At a glance
- Enness Global arranges large and complex finance for high-net-worth and ultra-high-net-worth clients.
- The firm works across mortgages, bridging finance, securities-backed lending, crypto-backed loans and luxury asset finance.
- Founded in 2007 and headquartered in Mayfair, Enness operates internationally and is regulated by the Financial Conduct Authority.
The new shape of private wealth
Private wealth has become harder for conventional lenders to read.
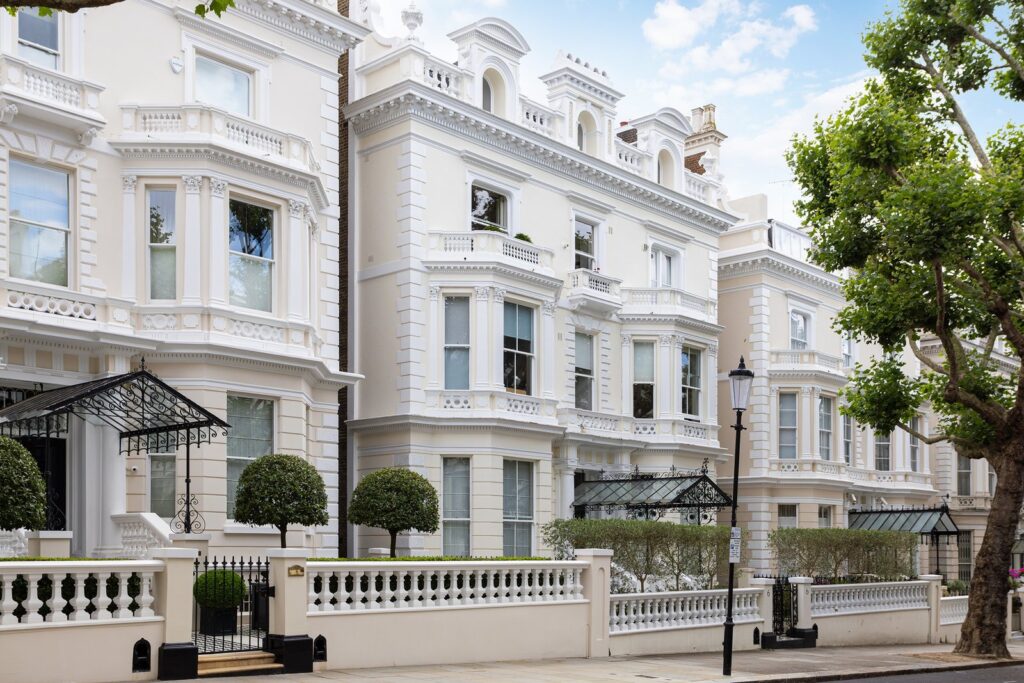
A single client may hold prime property in several countries, private equity interests, listed investments, digital assets and operating businesses, often across multiple jurisdictions.
For Robinson, this is where specialist finance earns its place. The question is not simply whether wealth exists, but whether it can be presented to a lender in a way that supports a credible loan structure.
Enness Global works with private banks, specialist lenders and alternative funders to arrange finance that reflects the full picture rather than one narrow slice of a client’s balance sheet.
The firm is headquartered in Mayfair and has offices in London, Dubai, Jersey, Geneva, Zurich, Nice and Monaco, giving it a natural role in cross-border transactions.
That international footprint matters because global mobility is no longer a fringe consideration for wealthy families and entrepreneurs. Many live between countries, buy homes in different markets and manage financial affairs through international structures.
Bridging finance as a tactical tool
Bridging finance is short-term funding, usually secured against property, designed for moments when timing is the main issue.
It can be used when a buyer wants to complete on a new home before selling an existing one, acquire a property at auction, fund a refurbishment or move quickly on a time-sensitive purchase.
For high-net-worth clients, bridging is often less about emergency funding and more about optionality. It lets a buyer act decisively without being forced to liquidate another asset at an inconvenient point in the market.
The structure of a bridging loan depends heavily on the borrower’s wider position, including assets, income profile, ownership structure and the intended exit route.
That exit route is crucial. As with any borrowing secured against property, the asset is at risk if the loan is not repaid, so certainty around repayment matters as much as the headline rate.
Borrowing against art, cars, yachts and securities
Alternative assets are playing a larger role in private finance as clients look to release liquidity without selling prized or strategically important holdings.
Property remains the most familiar form of collateral, but lending against fine art, classic and supercars, yachts, securities or private company shares requires a more specialised approach.
With fine art, lenders need comfort around provenance, authenticity, insurance and market liquidity.
With supercars, value can depend on condition, rarity, specification and resale demand.
With securities or private equity, the focus shifts to volatility, ownership terms and the practical route to repayment if circumstances change.
Behind these transactions sits a network of valuers, lawyers, tax advisers, private banks and specialist lenders, each viewing the same asset through a different lens.
The broker’s role is to understand those concerns early and shape a deal that releases capital without creating unnecessary friction.
Crypto-backed lending moves into the private client toolkit
Crypto-backed lending allows investors to borrow against digital assets such as Bitcoin or Ethereum rather than selling them.
For clients with substantial digital asset positions, the appeal is clear. They can access capital for property purchases, business investment or wider wealth planning while retaining exposure to potential long-term gains.
Robinson’s view is that the market has matured, but it remains specialist and demands discipline.
Volatility drives the structure of these loans. If collateral values fall, a lender may issue a margin call, requiring the borrower to add assets or repay part of the facility.
Loan-to-value ratios are therefore typically conservative, reflecting the speed at which digital asset values can move.
Used carefully, crypto-backed lending can be a powerful liquidity tool, but it is not a casual borrowing product.
Where Enness fits into the transaction
Enness Global’s work is centred on structuring, lender access and negotiation rather than simply introducing a borrower to a bank.
The firm arranges large and complex mortgages, bridging finance, securities-backed lending, crypto-backed loans, business finance and lending against luxury assets.
Its client base typically includes entrepreneurs, investors, international families and ultra-high-net-worth individuals whose financial lives don’t fit neatly into mainstream lending criteria.
That complexity is the point. The right structure can allow a client to preserve capital, remain invested and use borrowing as part of a broader wealth strategy rather than a blunt instrument.
As alternative assets become more accepted as collateral and wealthy clients continue to live and invest across borders, specialist finance is becoming less of a niche service and more of a core private client requirement.
For borrowers with significant assets but complicated circumstances, the value lies in turning a fragmented financial picture into a structure a lender can understand and support.